Global bond markets are undergoing a significant repricing of long-term borrowing costs. The U.S. 10-year Treasury yield recently touched 5.34%, its highest level since 2002. The UK 30-year gilt yield reached around 6.03%, its highest since 1998.
This is more than a conventional interest-rate cycle. It is a broader reset in the price of capital, particularly the cost of holding long-duration assets. Governments are running large fiscal deficits, inflation remains vulnerable to energy shocks, and corporations—particularly technology and AI companies—are competing with sovereign borrowers for long-term capital.
Why are global bond yields rising?
1. Fiscal borrowing, QT and the term premium
Governments are issuing increasingly large volumes of debt to finance fiscal deficits and refinance existing obligations. At the same time, the extraordinary support provided by Quantitative Easing (QE) has largely disappeared.
The Bank of England continues to reduce its gilt holdings through quantitative tightening (QT), while the Federal Reserve ended its balance-sheet runoff in December 2025. The important point is that central banks are no longer acting as the persistent, price-insensitive marginal buyers of government bonds that they were during the QE era.
A larger share of new issuance therefore has to be absorbed by private, price-sensitive investors. This can increase the term premium—the compensation investors demand for holding longer-duration bonds amid uncertainty about inflation, fiscal sustainability and future interest rates.
The pressure is compounded by the scale of U.S. borrowing. With U.S. national debt now above $40 trillion, persistent fiscal deficits are keeping Treasury issuance elevated, making the cost of refinancing increasingly important.
2. Inflation and “higher for longer”
Renewed energy-price pressures complicate the inflation outlook. Higher oil prices can feed into transportation, manufacturing and services costs, forcing markets to reassess how quickly central banks can cut rates.
3. Corporations are competing for capital
Governments are not the only borrowers. AI infrastructure, data centres and energy investment are creating substantial corporate demand for long-term capital. Five major hyperscalers—Alphabet, Amazon, Meta, Microsoft and Oracle—issued about $93 billion of bonds in 2025, versus an average of $35 billion annually in 2020–24; issuance had already reached roughly $132 billion by August 2026.
This reinforces the broader competition for long-duration capital: governments are borrowing heavily while corporations are simultaneously funding large-scale AI and infrastructure investment.
Why the reason for the yield rise matters
A bond yield rising because growth is accelerating is fundamentally different from a yield rising because investors are demanding compensation for inflation or deteriorating fiscal credibility.
The latter can create a much more difficult environment for financial assets because higher yields are accompanied by greater uncertainty about inflation, fiscal sustainability and the future path of interest rates.
What does this mean for equities?
Higher long-term yields increase the discount rate applied to future corporate cash flows, putting particular pressure on high-growth companies whose valuations depend heavily on distant earnings.
Higher bond yields also create greater competition for capital. When government securities offer materially higher returns, the equity risk premium can come under pressure.
At the same time, companies with significant debt face higher refinancing costs. Strong balance sheets, pricing power and sustainable free cash flow therefore become increasingly valuable.
This does not necessarily imply an equity-market collapse. Strong earnings can offset higher discount rates. But the environment becomes less forgiving: valuation expansion becomes harder and balance-sheet quality matters more.
Gold: the structural reserve-diversification trade
Gold faces a cyclical headwind from higher real yields and potentially a stronger dollar. But an increasingly important structural force is central-bank reserve diversification.
The change in official-sector buying over the past decade is striking:
| Period | Central-bank gold purchases |
|---|---|
| 2016–2020 | ~2,290 tonnes |
| 2021–2025 | ~4,500 tonnes |
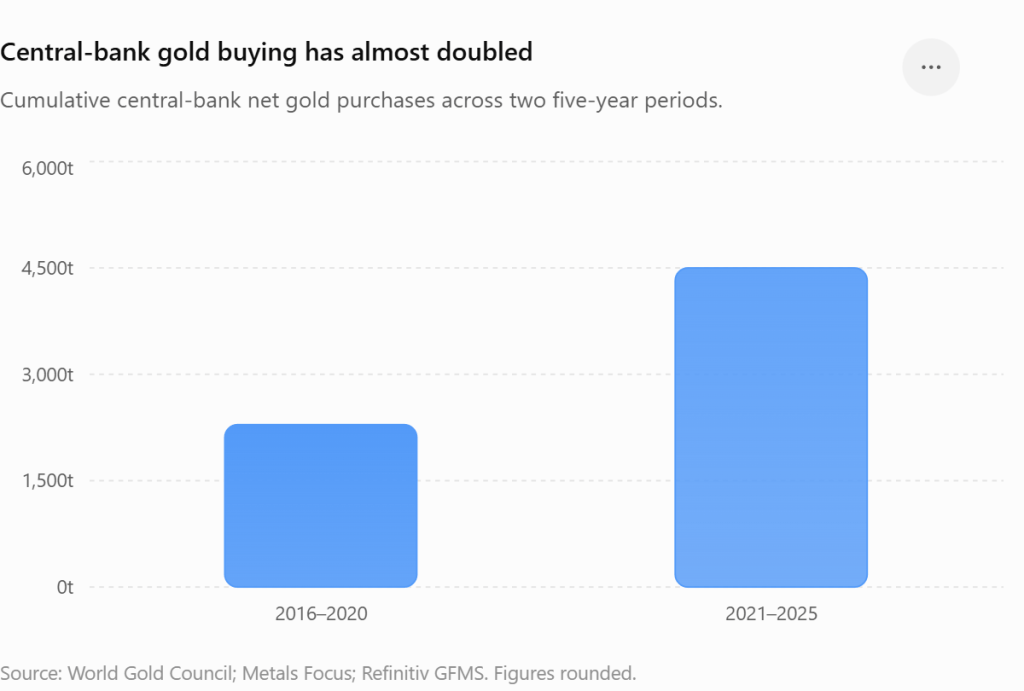
Central-bank gold accumulation has therefore almost doubled over the past five-year period, highlighting the growing importance of gold in reserve diversification.
The direction of travel is equally important. The dollar’s share of global reserves has declined from 71% in 2000 and 66% in 2015 to around 57% today. At the same time, the World Gold Council’s 2026 survey found that 89% of reserve managers expect global central-bank gold holdings to increase over the next 12 months, while 83% expect gold’s share of reserves to rise over the next five years; 74% expect the dollar’s share to decline.
This does not mean central banks are abandoning the dollar or Treasuries. Rather, it points to incremental diversification away from concentrated dollar exposure and toward a more diversified reserve architecture.
That distinction matters in a world of rising sovereign debt. Gold is not another government’s liability and carries no direct sovereign or corporate counterparty risk. Higher real yields can remain a cyclical headwind, but persistent official-sector accumulation provides structural support.
Silver: cyclical weakness, structural demand
Silver is more economically sensitive than gold, so fears of a manufacturing slowdown can pressure it when yields rise. Yet its industrial role provides an important structural counterweight.
Silver is widely used in photovoltaic cells, electrification, grid infrastructure and electronics. The Silver Institute expects another global market deficit in 2026, although thrifting and substitution in solar technology are reducing silver usage per unit of capacity.
Thus, silver combines a cyclical industrial risk with structural demand from electrification and constrained supply—potentially limiting downside compared with previous bear markets, although its volatility remains much higher than gold’s.
Emerging markets: a tougher policy environment
Higher developed-market yields can pull capital toward safer, higher-yielding assets, pressure EM currencies and increase the local-currency burden of dollar-denominated debt.
EM central banks therefore face a difficult policy dilemma: cutting rates can support domestic growth but weaken currencies and worsen imported inflation, while maintaining higher rates can restrain domestic demand.
The impact will vary. Economies with stronger external balances, manageable foreign-currency debt and credible monetary frameworks should be better positioned.
India: resilient economy, nervous market
India enters this environment with important structural advantages: domestic growth, infrastructure investment, a large internal market and a comparatively strong banking system.
But economic resilience does not mean immunity from global financial-market stress.
The recent correction in Indian equities illustrates this distinction. Rising global yields, elevated crude prices and foreign selling have increased investor caution. India’s equity market can therefore undergo a meaningful valuation correction even while the underlying economy remains relatively strong.
However, India’s market structure has also changed. Domestic institutional and retail flows—particularly SIPs and pension-linked savings—provide an important counterweight to FPI selling. SIP contributions reached ₹32,297 crore in August 2026, demonstrating the scale of recurring domestic investment.
This does not create a hard valuation floor. But it can reduce the probability of the disorderly capital-flight dynamics seen in earlier emerging-market crises.
With U.S. Treasuries yielding above 5%, foreign investors face a much higher hurdle rate when allocating to relatively expensive emerging-market equities. Domestic investors, meanwhile, continue investing through local savings flows.
India could therefore experience an orderly phase of multiple contraction rather than a classic currency-and-market crisis.
The key vulnerability remains crude oil: sustained high prices could widen the current-account deficit, increase inflationary pressure and weaken the rupee.
The bigger investment message
The global financial system may be entering a regime in which the cost of duration matters much more than it did during the ultra-low-rate era.
Governments need to borrow heavily. Corporations are undertaking enormous capital-investment programmes. Central banks are no longer providing the same persistent demand for duration that characterised QE. Inflation remains vulnerable to energy and geopolitical shocks, while investors are demanding greater compensation for holding long-term assets.
The implications are therefore broader than simply “higher bond yields.”
Equity valuations face greater pressure, highly leveraged companies become more vulnerable, emerging markets face tighter financial conditions, while gold benefits from an increasingly important structural force—reserve diversification.
For India, the message is nuanced: economic resilience provides a buffer, domestic flows provide market depth, but the recent correction shows that investors remain nervous about the global cost of capital, oil prices and liquidity.
The emerging regime can therefore be summarised in one sentence:
The world is moving from an era of abundant cheap capital toward an era in which capital is more expensive, duration carries a higher premium, and reserve diversification matters more.

